Two reasons come up often for Metro Atlanta rental owners: the property has appreciated, or the work of owning it has worn thin. Neither tells you whether the investment still belongs.
If you had this property's current market value in cash today, would you buy and operate this same rental—on financing you could get now, with its present condition, tenant, capital needs, and claim on your time?
Cash flow, capital needs, debt, equity, time, tenancy, marketability, concentration, and taxes each belong in the file before you decide. A hold, improve, or sell choice should follow from those facts, not from fatigue or from what you paid.
Important note: This article is general education. It is not tax, legal, securities, or financial advice.
Would You Buy This Property Again at Today's Price?
Purchase price records how the property entered the portfolio. It does not tell you whether the equity should stay. Appreciation since then is the same kind of fact: real, and already behind you.
Take a credible market value, subtract the loan payoff and realistic selling costs, and treat what remains as cash in hand. Would you use it to buy this rental again? Same operating load, same tenant situation, same repairs waiting, and a loan on terms you could obtain now rather than the rate you locked years ago.
An answer of no is a mismatch to price, not an order to sell. Operations, reserves, or management may be the part you can fix. Price those, then run the test again. What you should not do is decide from the original basis and call it analysis.
Rebuild Cash Flow Before You Judge the Investment
A common error is to subtract the mortgage from scheduled rent and call the difference profit. That figure skips vacancy, turnover, your time, and systems you already know are aging. Build a 12-month view a skeptical buyer would underwrite:
- Collected rent, not scheduled rent, after a realistic allowance for vacancy and credit loss
- Turnover: make-ready repairs, leasing fees, marketing, and rent lost between tenants
- Property taxes, insurance, and any utilities you pay
- Routine repairs and maintenance, kept separate from one-time capital projects
- Management, either a professional fee or the value of your hours at a rate you would actually accept for the work
- Reserves for items you can already name: HVAC, roof, water heater, and, where the property warrants it, drainage or foundation work
- Debt service, principal and interest
Set annual cash flow before taxes against current net equity: credible market value, minus payoff, minus realistic selling costs. The comparison is a screen. It leaves out principal paydown, future appreciation, taxes, and the year a capital item comes due. Thin cash flow on a large equity position, before your time and before work you can already see, is a reason to look harder. It is not, by itself, a reason to list.
Rapid paydown and light capital needs can still support a hold when you have no better use for the equity. If the screen is weak for a reason you can correct, correct it first. Make the rent roll honest. Get written estimates for deferred work. If time is the constraint, price management and rerun the statement. Some properties look marginal only because the owner is donating labor, or treating reserves as optional.
Do Coming Capital Projects Change the Plan?
Routine repairs are the cost of keeping a rental in service. Capital projects set the next few years: HVAC replacement, a roof, substantial plumbing or electrical work, drainage, structural issues, a major turnover rehab. Mixing the two is how an operating statement stays falsely comfortable.
Condition usually leaves a few distinct paths:
- Operate as-is with a funded reserve, accepting the rent current condition will support until a capital item can no longer wait
- Repair the item that is costing tenants or creating liability, and leave the rest on a schedule
- Renovate, then re-lease, only if higher rent, better tenant quality, or lower vacancy covers the spend and the carrying cost
- Sell as-is to an investor or rehab buyer, or do limited preparation if it widens the pool without improving past what that buyer will pay for
Inspections and written contractor estimates should decide among those paths, not a preference for how the kitchen ought to look. Renovation adds cost and time. It earns a place only when rent, vacancy, or sale price moves enough to beat using that cash elsewhere. The frequent miss is improving to a standard the likely tenant or buyer will not pay for.
If you are pricing targeted work before a re-lease or a sale, Renovation & Property Potential is a framework for that judgment. When condition, occupancy, title, or another complication makes an ordinary listing a poor fit, Complex Property Situations covers positioning and disclosure.
What Would You Actually Walk Away With?
The loan can argue for staying or for moving, and the two cases should not be blurred. A low fixed rate with years remaining is inexpensive capital of long duration. Replacing it, here or on the next property, may not be possible on similar terms. An adjustable loan near a reset, a balloon on a short horizon, or personal guarantees you want released can be a reason to choose your timing rather than have it chosen for you.
Get a current payoff and read the note: rate, fixed or adjustable, maturity, and any prepayment penalty.
Then estimate net proceeds, not a headline price. Start from recent comparable sales. Subtract the payoff, selling costs (commission, title, attorney, and transfer taxes), and credits or repairs a pre-market inspection is likely to require. What remains, before taxes, is the capital you could reallocate. An automated value is not that number.
Taxes, taken up below, can change both timing and structure. Settle them before you agree to a closing date. When the open questions are pricing, preparation, and positioning rather than whether to sell, see Resideum's seller representation.
What Is Your Time Worth, and What Does the Lease Allow?
Self-management that works only because you never invoice yourself is an unpriced job inside the return. Count the hours: calls, vendors, collection, turnovers. Value them at a rate you would recognize from your own work, or at what you would pay to be done with the task.
Selling because you are tired, without first pricing management, can mean giving up a favorable loan and a performing tenant to solve a staffing problem. Compare three paths with the cost included:
- Keep self-managing, with your time inside the cash flow so the return is comparable to a managed asset
- Hire management and convert uneven time into a known expense. Fees are often a percentage of collected rent plus leasing charges. They vary by manager, property, and market. Confirm the schedule in writing before you underwrite it.
- Exit and place the equity where it will ask less of you
Occupancy changes who can buy and how a sale runs. A stable, paying tenant on a longer lease gives an investor income to underwrite, and showings can be arranged with proper notice. Vacancy simplifies repairs, staging, and access, and it can bring owner-occupants, who in some cases may pay more than an investor buyer. You give up rent while the home is offered.
Access, notice, and any early end to a lease are governed by Georgia landlord-tenant law and by the lease itself. This is not a reading of either one. Speak with qualified counsel before you change access, end a tenancy, or plan a sale around a tenant's departure.
Who Would Buy It, and How Should It Be Shown?
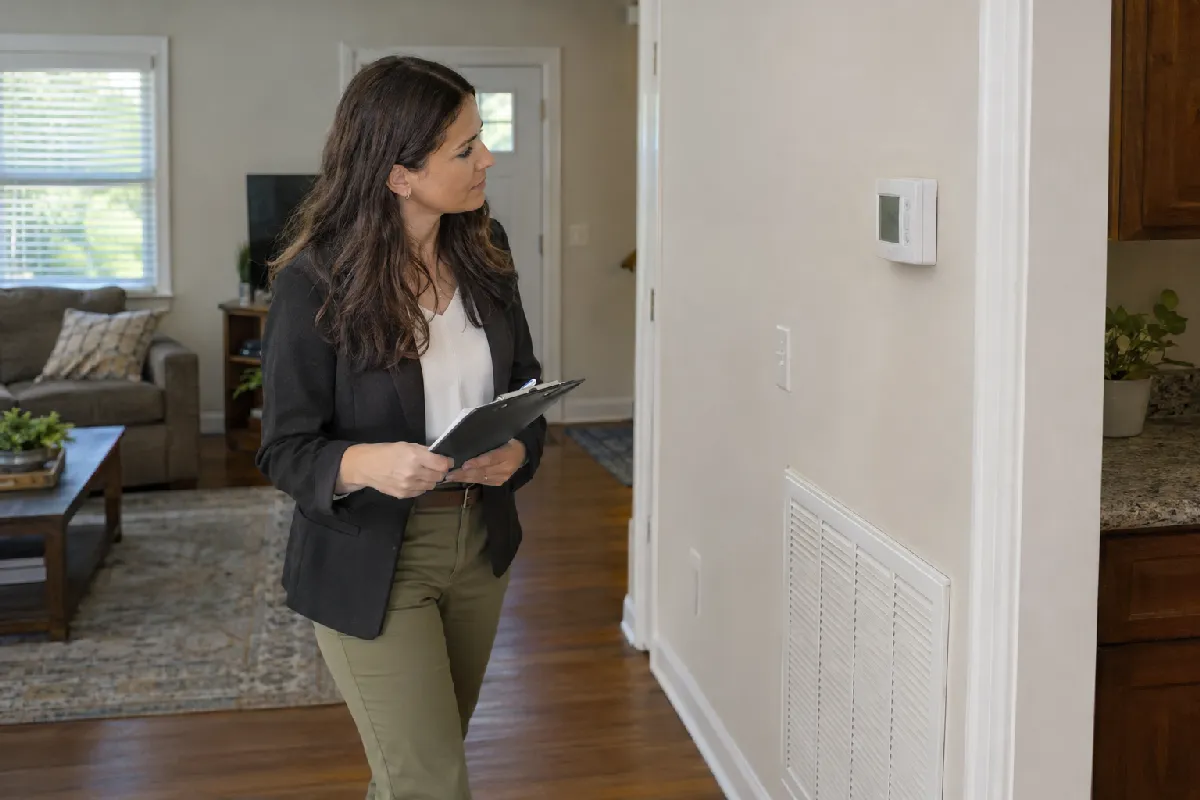
In Metro Atlanta, submarket, building type, condition, and buyer pool matter more than a regional headline. A single-family rental that an owner-occupant would also consider is a different sale from a small multifamily property whose logical buyer is an investor. Do not underwrite either with cap rates or absorption figures published for institutional apartments.
How you show the property has a cost either way:
- Occupied can document current income. It limits when buyers can walk through, and it often narrows the audience to investors.
- Vacant lets a buyer picture living there and makes repairs and staging simpler. It costs rent. Priced poorly, vacancy reads as distress rather than as a choice.
- Light preparation versus as-is: cleaning, paint, and basic repairs sometimes widen the pool enough to matter. In other cases an as-is sale to a cash or investor buyer is faster and nets more once carrying costs are counted.
Name the buyer you are addressing: investor, owner-occupant, or rehab buyer. Prepare for that buyer. A listing aimed at all three tends to serve none of them well.
What Else Could the Equity Do, and What Will Taxes Change?
Opportunity cost is the next realistic use of net proceeds, not a theoretical return on an ideal asset. That use might be another rental in a market you know, paying down more expensive debt, holding liquidity, consolidating several properties into fewer stronger ones, or moving toward holdings that need less of you as retirement gets closer.
Concentration can justify a sale even when a single property still produces an acceptable return on its own. If rental equity sits in one county, one property type, or one tenant profile, a local employment shift, a rule change, or a problem confined to that place hits the portfolio at once. Spreading the exposure can lower the modeled return and still make the portfolio more durable.
Personal limits belong in the comparison, not in a footnote. A need for simpler income, a retirement date, or a ceiling on how much landlord work you will do can outweigh a return that looks acceptable on a spreadsheet.
A sale may bring tax on appreciation and depreciation recapture. The amount depends on basis, holding period, depreciation already taken, and income. Ownership through an entity adds further questions. A 1031 exchange can defer gain when it is structured to meet the applicable requirements. The rules are technical, and the timing conditions are strict.
Leave the tax conclusion to a qualified tax professional who has your basis and your calendar. Do not list the property, accept an offer, or lock a closing date until you understand the tax cost and whether deferral or an installment sale fits.
When Holding Still Fits, and When a Sale May Be Cleaner
Holding is often the sounder choice when:
- Cash flow holds up after full expenses, management, and reserves
- Near-term capital needs can be funded, and the return on that cash is acceptable
- Existing financing is favorable and unlikely to be replaced on better terms
- The time burden is tolerable, or management can make it so
- You do not have a clearly better use for the equity
A sale deserves serious weight when:
- Large equity supports only thin income once reserves are honest
- Deferred maintenance or coming capital work will take cash the property cannot justify
- Loan terms create near-term risk: a rate reset, a balloon, or guarantees you want released
- Too much of the portfolio sits in one geography or one property type
- What you want has changed: simplicity, liquidity, or fewer doors
- The management burden is still high after operations have actually been fixed
The same set of facts can support different choices for two owners. Sentiment about the original purchase, or exhaustion you have not yet priced, is a weak basis for either one.
A Sequence for the Decision
Later steps depend on earlier ones. Work in this order:
- Estimate current market value from credible comparable sales or a broker opinion of value.
- Pull the payoff and read the terms: rate type, maturity, prepayment.
- Rebuild a 12-month operating statement with vacancy, management (paid or valued), and capital reserves included.
- Inspect and list capital projects for the next three to five years. Get written contractor estimates.
- Estimate net equity before taxes: market value, minus payoff, minus realistic selling and repair costs.
- Choose the operating path you will actually run: self-manage with time priced in, or hire management with fees priced in.
- Read the lease and the occupancy for what they do to timing, showing access, and any renovation sequence.
- Compare hold, improve, and sell against your objectives and against realistic uses of the equity.
- Review taxes with a qualified professional: gain, depreciation recapture, entity issues, and whether a 1031 exchange or another timing approach fits.
- Then carry out one plan: an operating and capital budget, or a sale with pricing, preparation, and a marketing timeline you can explain.
For a review built around one property and a stated set of goals, see Resideum's investor services.
Decide from the Property as It Is
Appreciation explains the past. Fatigue explains how the work feels. Neither replaces a current reading of value, debt, condition, tenancy, and time. Held to that standard, keeping the property and selling it can both be defensible.
If you want the review done on a Metro Atlanta rental you already own, start with an investor review. If the decision is already a sale, and the remaining questions are price, preparation, and who the listing should attract, see representation for the sale.