For Atlanta investors, the useful question is not only what representation will cost, but what the compensation buys. Brokerage compensation and scope are generally negotiable. They can vary with the agreement, the property type, and how much work the transaction actually requires. A lower fee can mean a narrower scope. A higher fee is not automatically better service. This guide covers how investor representation is often structured, the fee models you may see, what an investment-focused broker may deliver, how that work can differ from ordinary buyer representation, and what to clarify before you sign.
Start with the better question: What do you get for the compensation?
The headline rate tells you very little by itself. What usually matters is the quality of the analysis, how offers are negotiated, whether risks are identified early, and how the work is carried through due diligence and closing. Before you compare numbers, ask what the broker will do, what you will receive, and whether that work fits the strategy you are actually pursuing.
Assignments are not interchangeable. A search for a stabilized rental with a defined buy box is a different job from a distressed property with permit questions, renovation unknowns, and unusual financing. Short-term holds, value-add projects, and build-to-rent portfolios each change the workload. Evaluate the fee and the scope together.
How investor representation is structured: a written, negotiated agreement
Investor representation is commonly set out in a written, negotiated agreement. That document typically governs services, duties, exclusivity, and how and when compensation is earned and paid. Read the full agreement. If a term is unclear, confirm it in writing before you rely on it. For legal questions, consult a qualified attorney.
Define the scope of service
The agreement should say which property types are covered—single-family, small multifamily, condos, townhomes, portfolios—and the geographic focus, whether that is specific Atlanta submarkets or surrounding counties. It should also say what is included and what is not. Strategy sessions, search and screening, preliminary underwriting, offer preparation, negotiation, due diligence coordination, renovation input, and closing logistics should each be addressed, not left implied.
Term, exclusivity, and termination
Check the length of the agreement and whether it is exclusive. Understand termination rights, the notice required, and any protected period after the agreement ends. Ask how off-MLS and investor-found properties are treated, and whether they fall inside the agreement or outside it.
Compensation language and timing
The agreement should state how compensation is calculated, when it is earned, and when it is payable. If another party may contribute—such as the seller or the listing side—confirm how that amount is credited and whether any shortfall remains your responsibility.
Conflicts and outside payments
Ask for disclosure of referral fees, affiliated entities, and vendor relationships. Understand whether the broker may accept compensation from more than one party, and how that is handled if it creates a conflict with your instructions.
How compensation is established and paid: structures and clarity
Compensation is defined in the agreement and the transaction documents, not by custom. Do not assume investor representation is free, or that the seller or listing broker will pay the buyer-side fee. That practice varies by transaction. It is not guaranteed.
Common fee models you may see
Investor representation is often structured in one of these ways:
- Percentage of purchase price
- Flat fee per transaction
- Hourly or consulting arrangements
- Retainers or transaction fees
- Hybrid structures that blend the above
Each model trades something. A percentage can align compensation with completing the purchase and with deal size, but the same rate can feel high on a large or relatively simple acquisition. A flat fee is easier to budget, though it may not track the work if the assignment grows. Hourly or consulting arrangements can fit a defined task, such as an underwriting review, if the scope and billing limits are written down. A retainer can suit an investor planning several transactions or ongoing strategy input, provided it is clear what the retainer covers and what still triggers a separate fee.
Who may pay and how credits work
A seller or listing side may offer to contribute to buyer-side compensation. Confirm whether that payment is credited against what you owe, and what you owe if the contribution is partial or absent. In one transaction, an outside payment may cover the fee. In another, you may owe some or all of it. Settle that before you are under contract, not at the closing table.
Written-agreement expectations before home tours
Some brokerages require a signed agreement stating compensation terms before you tour properties. Whether that expectation applies to virtual showings, or to visits arranged for tenants or investors, depends on the firm and the market. Ask how touring, disclosure, and compensation are handled before you start looking.
Why fees vary: scope, complexity, and deliverables drive the workload
Not every investor assignment is the same amount of work. A higher fee is easier to judge when it is tied to defined deliverables, not to a general claim of expertise.
Compare the work, not a standard rate
Start with the assignment in front of you. A stabilized rental with clear criteria and conventional financing may call for screening against a buy box, standard offers, inspection coordination, and closing management. A property that needs renovation, has unresolved permit questions, or depends on repositioned rent assumptions usually adds contractor access, scope review, and more contingency negotiation. An out-of-state buyer who needs on-the-ground screening and vendor coordination will often take more of the broker’s time than a local investor running a repeatable buy box with existing relationships. The fee conversation should follow that difference in work.
Variables that change the work
These factors commonly change the workload, and therefore the compensation worth negotiating:
- Asset type and condition
- How many properties are screened, and how long the search runs
- How deep the underwriting and renovation analysis goes
- Due diligence issues, including leases, inspections, environmental questions, and title
- Financing structure and appraisal risk
- Negotiation intensity and the access needed for contractors and vendors
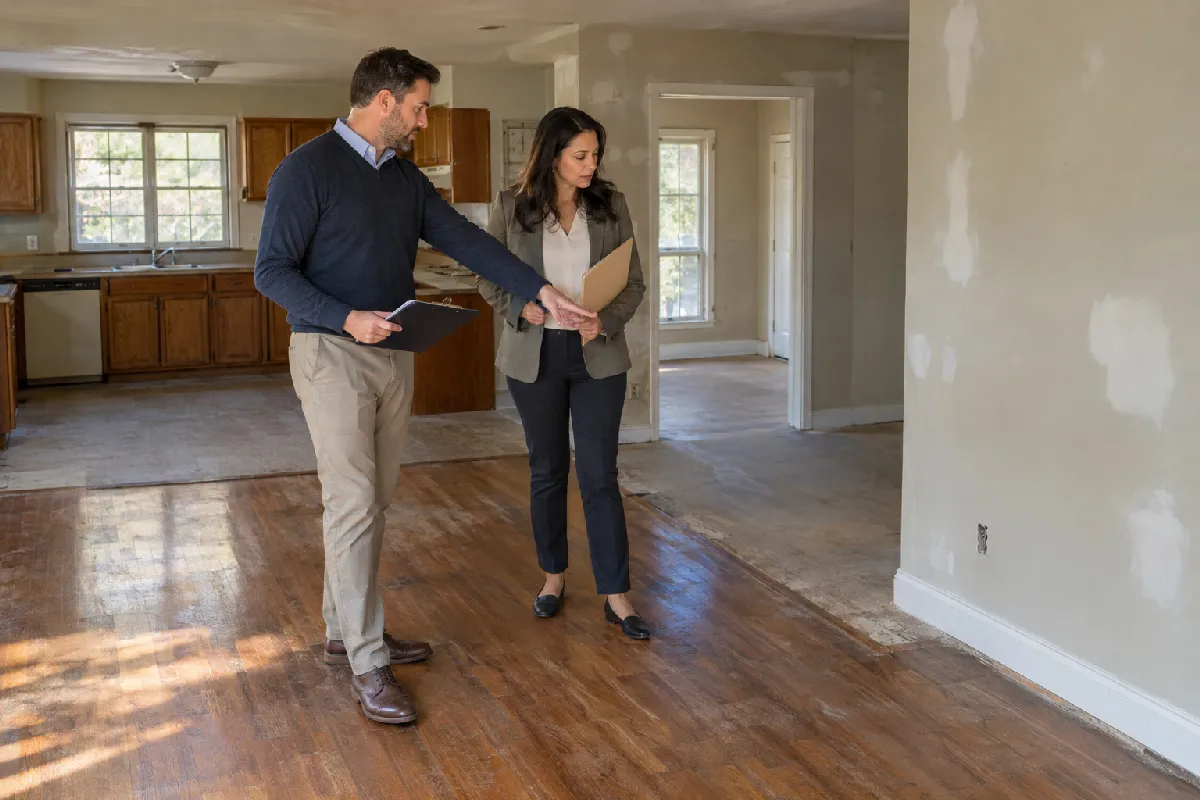
What an investment-focused broker may provide (beyond access and paperwork)
Services differ by agreement. Confirm what is included before you count on it. For one description of acquisition support, review Resideum's Investor Services page, then match that description to the written scope.
Strategy and buy-box clarity
Agree on target returns, hold period, property type, rent range, renovation appetite, and exit options before the search starts. Without that, screening time goes to properties that do not fit the model.
Screening and preliminary analysis
The broker may help test rent and vacancy assumptions, operating costs, taxes, insurance, reserves, and financing sensitivity. Treat those figures as working assumptions. Rents, expenses, and loan terms can all move, and none of them is a projection the broker can guarantee.
Renovation and value-add vetting
On a value-add property, useful help is often practical: likely scope, a rough cost range, access for contractors, and a realistic timeline. This renovation screening discussion is a starting frame, not a bid. Confirm cost and timing with the people who will do the work.
Offer structure and negotiation
Price is one term. Due-diligence length, earnest money, inspection rights, access, financing and appraisal contingencies, existing leases, and closing timing all affect risk and operations. An investment-focused broker should know how to keep enough room to finish the analysis and to exit cleanly if the numbers do not hold.
Due diligence and closing coordination
Coordination can include inspections, rent-roll checks, vendor access, and contingency deadlines, along with communication among the lender, title, attorney, and property manager. Confirm which of those tasks sit inside your agreement and which you are expected to manage.
Professional boundaries
A broker is not a substitute for an inspector, contractor, attorney, CPA, appraiser, lender, or property manager. The useful role is to coordinate the process and help you interpret findings within the agreed scope—not to provide services that belong to another license.
How investment representation differs from ordinary residential buyer agency
Investment representation usually adds underwriting and strategy: rent and vacancy assumptions, operating costs, renovation planning, financing sensitivity, and whether an exit is realistic. It also tends to weigh terms that affect risk, access, and operations more heavily than a purchase arranged mainly around how a home will live day to day. The core purchase tasks—access, contract preparation, and process management—typically remain. The investment analysis is layered on top, and only to the extent the agreement says so.
A residential buyer agent often centers location, daily use, and condition. An investment-focused broker often centers cash flow, risk-adjusted return, renovation feasibility, and exit liquidity. Those are general distinctions. The written agreement is what governs.
Atlanta factors that can shape scope and cost
Across the metro, submarkets differ in tenant demand, taxes, insurance, renovation norms, and resale liquidity. Inspection expectations, permitting, and HOA rules can also differ by county and municipality. These are planning factors, not a market forecast.
The practical effect is time. Scheduling contractors, working through HOA or municipal steps, and moving between counties all take coordination. That matters more when the buyer is not local and needs screening and vendor introductions handled on the ground.
Evaluate before you sign: a compact decision framework
Clarify the strategy and the level of help you actually need. Compare deliverables side by side, not only the fee. Run compensation through more than one payment scenario: the seller or listing side pays all, part, or none. Agree on communication, responsiveness, and who watches deadlines. Then read exclusivity, term, termination, and any protected period as carefully as the fee clause.
When a percentage makes sense
A percentage often fits full-scope support across search, negotiation, and closing, especially when you want compensation tied to completing the transaction. It can also scale in ways that feel high on a large or simple deal. Match the percentage to the work, not to habit.
When a flat or hybrid/consulting model makes sense
A flat fee, hybrid, or consulting arrangement can fit targeted underwriting, due-diligence help, or a first look at a new asset type before you scale. It can also fit an investor who already has deal flow and needs episodic input rather than full transaction management. The tradeoff is that a narrow scope stays narrow unless you amend it.
Questions to ask before signing a representation agreement
Services and analysis:
- What, specifically, is included in screening and preliminary underwriting?
- Will you help evaluate renovation scope and arrange contractor access?
- How are off-MLS and investor-found properties handled?
Compensation and payment:
- How is compensation calculated, when is it earned, and when is it paid?
- If the seller or listing side pays nothing, or only part, what do I owe?
- Are there retainers, transaction fees, or hourly components?
Process and negotiation:
- How do you structure offers to protect due-diligence access and timelines?
- What do you recommend when competition pushes toward waiving protections?
Conflicts and vendors:
- Do you have affiliated businesses or referral arrangements, and how are they disclosed?
- Can you offer more than one option for inspections, contracting, and management?
Agreement mechanics:
- Is the agreement exclusive? What is the term, the termination process, and any protected period?
- What changes require an amendment?
Boundaries:
- Which specialists—inspector, attorney, CPA, lender, appraiser, property manager—will I still need to hire?
Common mistakes that raise cost or risk
Chasing the lowest headline fee without confirming scope is a common way to buy the wrong service. Assuming the seller or listing broker will cover buyer-side compensation can produce a surprise at closing. An agreement that is vague on termination, the protected period, or off-MLS properties creates the same problem later, when it is harder to unwind.
Other mistakes sit in the deal itself. Skipping renovation vetting, or building the purchase on rents that are hard to support, can erase any savings on the fee. Treating price as the only term that matters leaves access, contingencies, and timing unexamined. Waiving due-diligence protections without a clear reason can cost more than the compensation you tried to reduce.
There is no single standard Atlanta rate for investor representation. Compare compensation with scope, analysis, negotiation, and due-diligence support. Read the agreement, test how the fee works if outside payment changes, and make sure the services match the property type and the strategy.
To see how an acquisition-focused scope can be described, review Resideum's Investor Services overview. For a contrast with general buyer support, see the Buyer Representation page.